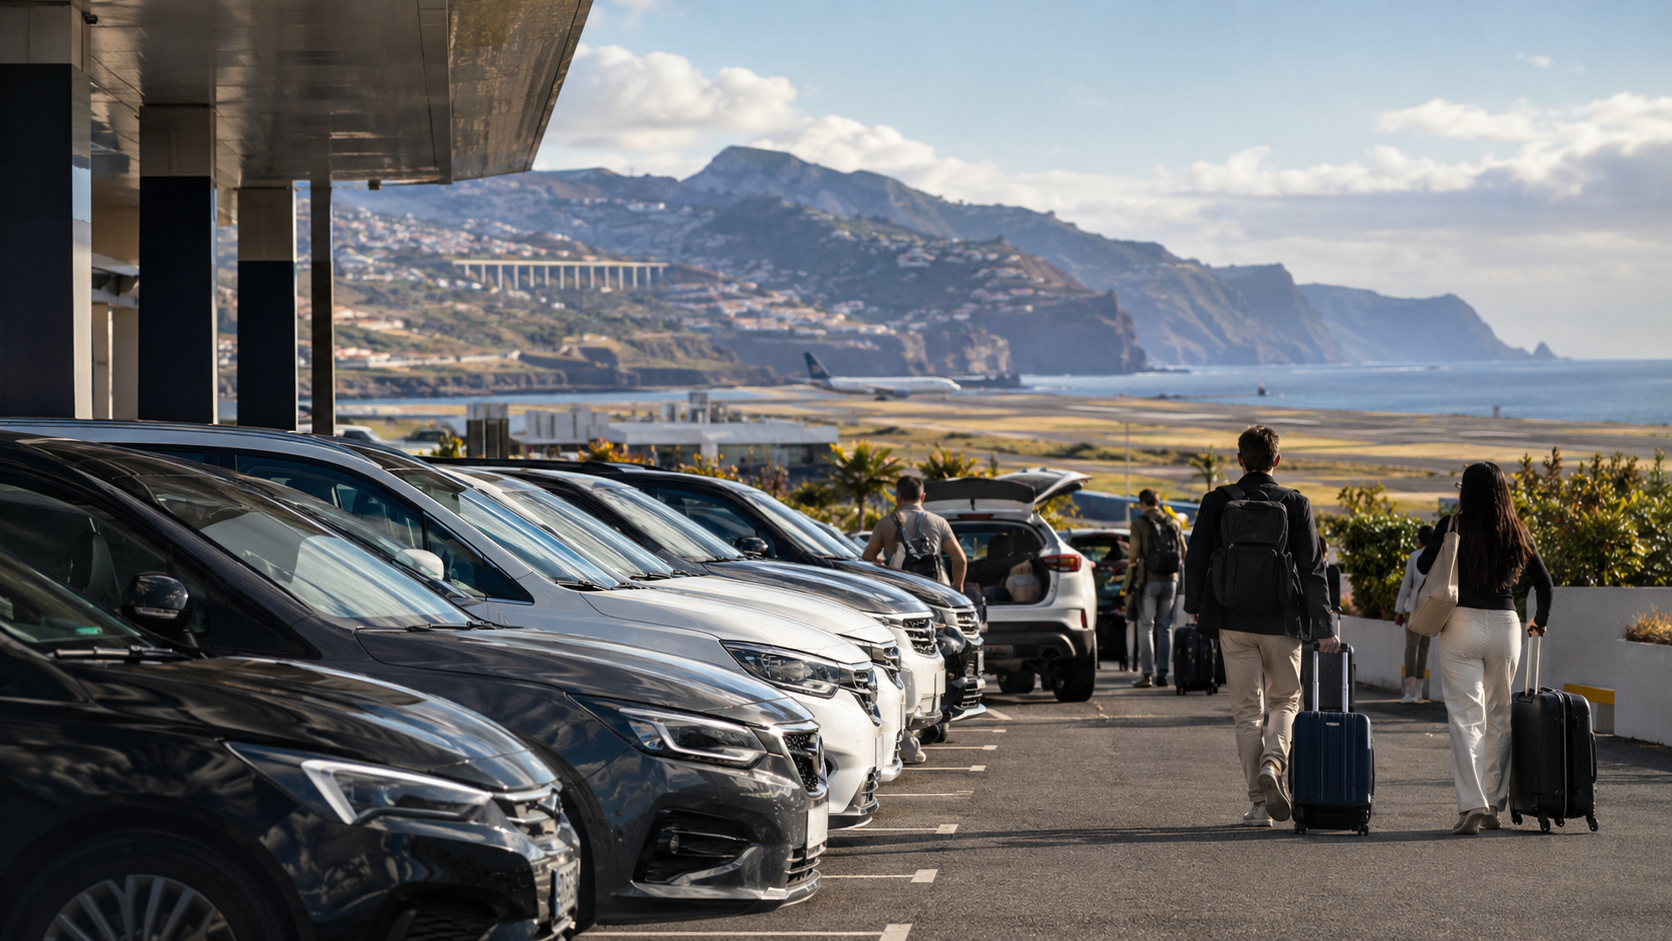
At the end of the second quarter of 2026, Madeira’s car rental fleet was 5.8% larger than a year earlier. Over the same quarter, rental contracts increased by 2.6% and airport passenger traffic by 2.4%. Revenue, however, rose by 7.1%. The picture is far from straightforward, particularly at a time when a new usage fee and tighter requirements on parking and fleet composition are coming into force.
The discussion around car rental in Madeira took on a different dimension in 2026. It is no longer just about tourism demand, vehicle availability or peak-season pricing. Fleet size is now increasingly linked to wider questions around mobility, parking, pressure on the territory and sustainability.
In this context, it is easy to fall into one of two interpretations: either there are too many rental cars on the island, or this is simply further regulation of an industry that has expanded alongside tourism. The available data do not convincingly support either conclusion when framed that simply.
What they do allow is a better understanding of where the risk may lie.
Madeira has a rare advantage for this type of analysis. The Regional Directorate of Statistics of Madeira (DREM) publishes specific information on the sector, including fleet size, rental contracts, average rental duration, pick-up locations and revenue. The 2026 figures are still provisional, but they already allow us to connect capacity, demand and revenue with a level of detail that is unusual in Portugal.
A fleet growing faster than demand
At the end of the second quarter of 2026, 14,025 vehicles were allocated to the car rental sector in Madeira, 5.8% more than a year earlier.
Between April and June, 124,750 rental contracts were recorded, representing year-on-year growth of 2.6%. For passenger cars, which account for the vast majority of the fleet, average rental duration fell by 2.5%, to six days. Over that same quarter, passenger traffic at the region’s airports increased by 2.4%.
| Madeira – Q2 2026 | Year-on-year change |
|---|---|
| Fleet at quarter-end | +5.8% |
| Rental contracts | +2.6% |
| Airport passengers | +2.4% |
| Average duration – passenger cars | -2.5% |
| Sector revenue | +7.1% |
| Base rental revenue | +7.2% |
The gap is large enough to deserve attention. At the end of the quarter, the number of vehicles had increased proportionally more than either contracts or air traffic.
That does not, however, allow us to calculate a precise decline in fleet utilisation. The 14,025 vehicles represent the fleet at the end of the quarter, not the average number of vehicles available every day throughout April, May and June. Nor is there a public dataset showing available fleet days and actual rental days that would allow a precise 2025 versus 2026 comparison.
Claiming that utilisation fell by 5% or 6%, for example, would go beyond what the data support. What we do have is an indication that capacity may be expanding faster than the demand actually captured by the sector.
For anyone managing a fleet, that is already a relevant signal.
More passengers do not automatically mean more rentals
During the first six months of 2026, Madeira’s airports handled approximately 2.769 million passengers, up 3.1% year on year. July continued at almost the same pace: 580,100 passengers, +2.9%, taking January-to-July growth to 3.0%.
There is no evidence here of weakening tourism demand. There is growth, just at a relatively moderate pace.
The issue is that one additional airport passenger does not necessarily translate into one additional rental contract. Taxis, private transfers, ride-hailing services, public transport, organised excursions and changes in the way visitors move around during their stay all make that relationship less direct.
During the first half of the year, for example, 213,835 car rental contracts were recorded, 0.7% fewer than in the same period of 2025. That comparison needs to be treated cautiously, as DREM itself notes that first-quarter results were affected by the closure of companies that had been part of the reporting universe in the previous year. Even so, the figures help explain why tourism growth should not automatically be translated into an equivalent forecast for car rental.
There are also significant differences within the market itself.
In the second quarter, 61.6% of contracts had the airport as the pick-up location, and these contracts grew by 9.8%. Contracts collected from rental company premises fell by 4.8%, while hotel pick-ups declined by 15.9%.
A company with a strong airport presence may therefore have experienced a very different quarter from one more dependent on hotels or off-airport locations. The regional average hides part of that reality.
Fleet planning is not simply about how many vehicles are available. It also depends on where they are, which segment they serve, which channel generates the booking and when that capacity is actually needed.
The figure that complicates the overcapacity argument
If the analysis stopped at vehicles, contracts and passengers, it would be relatively easy to build a case around overcapacity.
Revenue points in a different direction.
During the second quarter, the companies covered by DREM’s survey generated €33.2 million, an increase of 7.1% year on year. Base rental revenue accounted for €26.6 million and grew by 7.2%, while other revenue increased by 6.6%.
Revenue therefore grew substantially faster than the 2.6% increase in rental contracts.
Dividing total revenue by the number of contracts — an indicative calculation, not an official DREM metric — gives approximately €266 per contract in Q2 2026. Based on the relative growth of revenue and contracts, this represents an improvement of around 4% compared with the previous year.
This is not ADR, nor is it Revenue per Rental Day, because we do not know the exact number of rental days associated with the full universe of contracts. It does, however, show that the average value generated per contract increased.
We see something similar across the first half of the year: despite a slight decline in the number of contracts, revenue increased by 5.8%, to €50.8 million.
The public data do not tell us how much of that improvement came from base rate, vehicle mix, stronger pricing during peak periods or ancillary products. But they do prevent an overly simplistic conclusion about fleet growth.
A business with very high utilisation can still destroy margin if it has to discount too aggressively to get the last vehicles onto the road. Another may operate at a lower utilisation level, preserve a healthier average rate and generate more ancillary revenue per contract. The reverse is equally true: high prices cannot indefinitely compensate for an oversized fleet sitting idle.
What matters is the combination of utilisation, revenue generated per rental day and the cost of keeping that capacity available. That is precisely where the public data stop short.
A new usage fee enters the equation
It was against this backdrop that a new usage fee came into force on 1 June 2026.
The charge is €2 for each full 24-hour rental day, up to a maximum of ten days per contract. For zero-emission vehicles, the amount falls to €1. A conventional rental subject to six full days of the fee therefore adds €12 to the amount paid by the customer.
The operator is responsible for collecting the amount and passing it on to IMT, IP-RAM. In return for administering the process, operators receive compensation equal to 2.5% of the fees effectively collected and remitted, plus VAT where applicable.
The measure has been contested. ACIF-CCIM focused particularly on the impact on bookings that were already in place and, in a survey of 15 companies, identified 23,980 contracts and around 175,000 rental days potentially affected.
From a fleet-management perspective, however, it is worth separating the issues. The fee applies when the vehicle is rented and being driven. The rationale presented by the Regional Government is linked to the impact of that use on mobility and the territory, rather than specifically to vehicles sitting idle.
The link with unused capacity becomes much more direct when we look at the new parking requirements.
When the cars are not being rented
Operators are now required to have a fixed, duly licensed parking area located within a maximum radius of 15 kilometres in a straight line from their fixed establishment or from the delivery location with the highest level of activity.
The minimum capacity has been set at 20% of the fleet. For existing operators, the calculation is based on the average annual fleet derived from the previous four reported quarters, with a transition period before full compliance is required at the end of 2027.
One point is worth clarifying because it has appeared repeatedly in discussions around the new rules: there is no requirement to keep 60% of the fleet in covered parking. The regulated minimum parking capacity is 20%, and the legislation does not require the parking area to be covered.
There is, however, another rule with potentially greater operational consequences: rental vehicles that are not currently rented may not remain parked on public roads, although other locations specifically designated for the activity may also be used.
That changes the economics of an idle vehicle. Depreciation and capital costs remain, but lower utilisation can now also increase the amount of physical space required to accommodate the fleet. On an island, where available space naturally comes with additional constraints, that becomes more significant.
The fleet itself will also have to change
The new framework adds another requirement concerning fleet composition: 10% of the operational passenger-car fleet must consist of zero-emission vehicles. Existing operators have until the end of 2027 to adapt.
According to DREM’s Q2 2026 statistics, vehicles classified as electric accounted for 1.6% of the total fleet, while hybrids represented 8.4%.
These figures should not be treated as directly comparable. DREM’s statistics refer to the entire fleet, while the legal requirement applies specifically to operational passenger cars and uses a defined legal concept of a zero-emission vehicle. They do, however, give an indication of the scale of the transition that future fleet-renewal cycles will need to absorb.
For operators already preparing their 2027 fleets, the decision will therefore involve more than purchase price, residual value and expected demand. Powertrain, charging infrastructure and the suitability of these vehicles for customer use will increasingly form part of the same calculation.
So, are there too many rental cars in Madeira?
Based on the available evidence, we cannot answer yes.
There are reasons to ask the question. At the end of the second quarter there were 5.8% more vehicles than a year earlier, while during the quarter rental contracts increased by 2.6%, airport traffic by 2.4%, and the average duration of passenger-car rentals declined.
At the same time, revenue increased by 7.1%.
Those two sides of the equation cannot be separated. Revenue growth does not prove that expanding the fleet was the right decision: if generating that additional revenue required too much capital, depreciation, parking and other costs, the return may still have deteriorated. But a fleet growing faster than passenger numbers does not, by itself, prove that there is excess capacity either. Some companies may be gaining market share, individual locations are behaving very differently, and certain segments may be growing substantially faster than the regional average.
To reach a firmer conclusion, we would need data such as average available fleet, rental days, utilisation, comparable daily rates, defleet volumes, costs and margins.
Until then, “excess fleet” should be treated as a hypothesis to monitor, not a conclusion.
What we already know is relevant enough. Tourism continues to grow, but at a pace closer to 2%–3%. The fleet reported at the end of the quarter increased more quickly and, at least through June, the sector managed to grow revenue faster than both.
This is where the new regulatory environment becomes particularly relevant. More capacity means more capital and more space to accommodate vehicles when they are not rented, while the composition of the fleet itself will also have to change over the coming years.
For the Regional Government, the number of rental vehicles on the island is also a question of mobility and the use of public space. For an operator, the question is inevitably more specific: what return does the last car added to the fleet actually generate?
The answer cannot be found only in tourist numbers or fleet utilisation. It lies in the combination of days sold, achieved rate, ancillary revenue, the cost of keeping capacity available and, ultimately, margin.
For many years, more tourism could be enough to justify more cars. The 2026 data suggest that this relationship now deserves much closer scrutiny.
Every additional vehicle will increasingly need to justify the capital, space and cost it occupies within the operation.